Residency is decided by facts, not by a date you choose
A nurse from Ontario takes a two-year contract in Lisbon, keeps her house and leaves her spouse behind in Canada. Her ticket has a date on it, but that is not the day she stops being resident. A home in Canada and a spouse or common-law partner in Canada are significant ties, and with those she is usually a factual resident of Canada, not an emigrant.
The day matters because two things turn on it: the deemed sale of most of what you own, and which of your income Canada can still tax. The Canada Revenue Agency (CRA) weighs all the facts, including your residential ties and the length, purpose, intent and continuity of your stay abroad. Dependants in Canada are the third significant tie. Secondary ties are considered together: personal property in Canada such as a car or furniture, social ties such as memberships in Canadian organisations, economic ties such as Canadian bank accounts or credit cards, a Canadian driver's licence or passport, and health insurance with a province or territory.
One exception. If you are also resident in a country with a tax treaty with Canada, you may be a deemed non-resident, and the treaty's tie-breaker rules decide. For the CRA's opinion rather than your own reading, there is Form NR73, Determination of Residency Status (leaving Canada). How long a reply takes: not published; ask the CRA before you plan around one. [T1] [T2] [T8]
The departure date and what it changes
Three dates compete, and generally the latest wins: the day you leave Canada, the day your spouse or common-law partner and dependants leave, and the day you become a resident of the country you settle in.
Up to that date you report income from all sources. After it, you pay Canadian income tax only on Canadian-source income, and some of that is taxed by withholding at source instead of on a return. You enter the date on page 1 of the return for the year you leave, and if you decide you do not have to file, the CRA still asks to be told the date.
Tell Canadian payers and financial institutions that you are no longer a resident. As a non-resident you are generally not eligible for the Canada child benefit or the Canada Groceries and Essentials Benefit, and if payments continue you should contact the CRA immediately. Provincial health cover ends on its own schedule, covered in health cover when you retire abroad from Canada. [T1]
The deemed disposition, known as departure tax
Nothing is sold and no money arrives, yet a gain can be taxed. When you leave, the law treats you as if you had sold most of what you own at fair market value and bought it back immediately for the same amount. Any gain on paper can be taxed as a capital gain. The CRA's examples are shares, jewellery, paintings and collections, inside or outside Canada.
Some property is excluded, following section 128.1 of the Income Tax Act. That covers real property in Canada, Canadian resource property and timber resource property, and business property of a business run through a permanent establishment in Canada. It covers registered plans and pensions (RRSPs, RRIFs, RESPs, RDSPs, TFSAs, FHSAs and pension plans, among others). It also covers property you owned when you last became a resident, or inherited since, if you were resident in Canada for 60 months or less in the 10 years before you left. The last exclusion has conditions, so read the Act's wording before you rely on it. A later sale of Canadian real property falls under separate non-resident procedures.
The gain is worked out on Form T1243 and reported on Schedule 3 of the return for the year you leave. How large yours is depends on what you hold, what you paid and what it is worth on the day. [T3] [T4]
Reporting it, deferring the tax and posting security
$25,000 is the line for Form T1161, List of Properties by an Emigrant of Canada. If the fair market value of everything you owned when you left was more than that, the CRA asks for the form. It leaves out cash, the registered plans above, and personal-use items such as household effects, clothing, cars and collectibles worth less than $10,000 each. It is due by your filing due date even if you do not otherwise have to file, and the late penalty is $25 a day (minimum $100, maximum $2,500). If your total is anywhere near $25,000, prepare to file it.
You can elect to defer payment of the tax, whatever the amount, by filing Form T1244 by 30 April of the year after you leave. You then pay later, without interest, when you sell the property. When you do sell a deferred asset, you send the CRA the details and the tax is due by 30 April of the following year.
Security comes in above a threshold. If the federal tax on the deemed disposition is more than $16,500 (more than $13,777.50 for former Quebec residents), you must provide adequate security, and may need to cover provincial or territorial tax too. If your estimate is close to that, assume security applies and contact the CRA before 30 April. What counts as acceptable security: not published; ask the CRA. [T3]
RRSPs, RRIFs, TFSAs and FHSAs after you leave
A retiree who moves abroad and keeps drawing from a RRIF will see tax withheld at source. Leaving does not trigger tax on these accounts, because they are excluded from the deemed disposition. What changes is what happens when money comes out or goes in.
RRSP and RRIF payments to a non-resident are Part XIII income. Your payer withholds tax at a usual rate of 25% unless a tax treaty reduces it, and that is generally your final Canadian tax on the income. Treaties can treat periodic payments differently from lump sums (Information Circular IC76-12 covers the rates), so the rate for your destination depends on the treaty text; the CRA's non-resident tax calculator settles it. For certain pension income you can elect under section 217 to file a Canadian return and be taxed at resident rates.
You can keep a TFSA. Canada does not tax the income earned in it or withdrawals, though your new country may. A contribution made as a non-resident is taxed at 1% for each month it stays in the account, and you build no new room for a year in which you are non-resident throughout. Amounts you withdraw while abroad are added back to your room only when you become resident again.
The FHSA also continues, except that you cannot make a qualifying withdrawal to buy or build a home while a non-resident. Taxable withdrawals face 25% withholding unless a treaty reduces it. [T3] [T4] [T5] [T6] [T8] [T9] [T10]
CPP and OAS payments abroad, and Form NR5
Non-resident tax on Canada Pension Plan (CPP) and Old Age Security (OAS) payments is deducted automatically at 25% unless a treaty reduces it. This is separate from eligibility, which the health cover article covers for OAS.
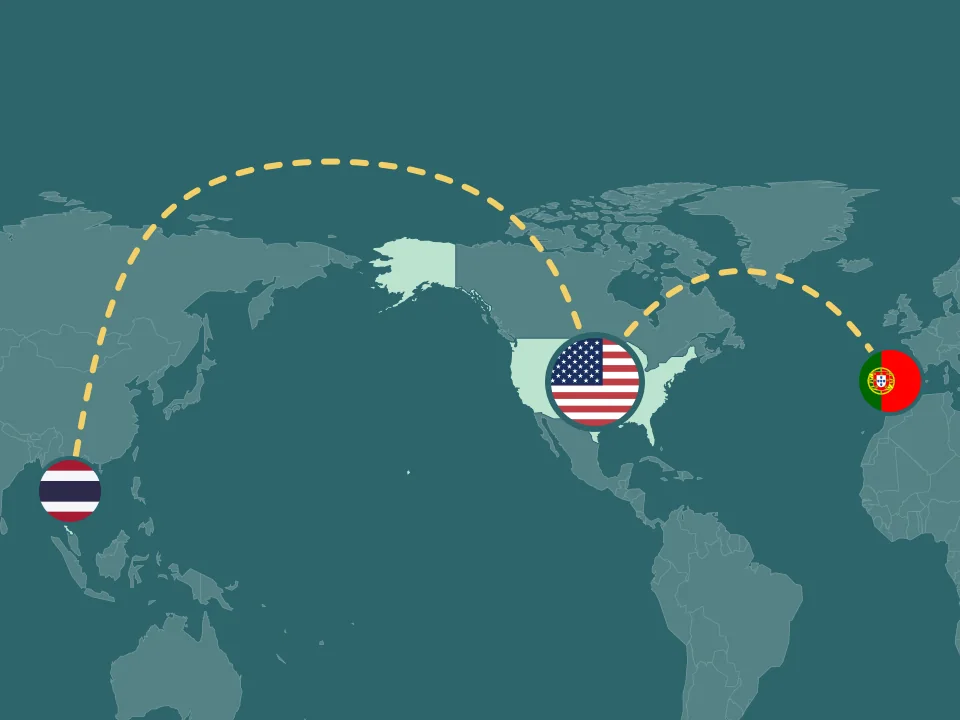
By country of residence, the rate is 15% on OAS and on CPP or QPP for Spain, Mexico, Malaysia and Portugal. Portugal also exempts the first CA$12,000 of your Canadian pensions if you file Form NR5. Italy is 15% on CPP or QPP and 25% on OAS, with the same NR5 exemption excluding OAS. France, Thailand and Costa Rica have no rate listed, so ask the CRA for theirs.
Form NR5 asks the CRA to reduce the withholding. You usually need to file it only once every five tax years, but it commits you to a section 217 return for each year it covers, due by 30 June of the following year. Miss that and you owe the full tax, less what was withheld. OAS recipients abroad may also have to file the Old Age Security Return of Income each year, though you may not need it in a treaty country. [T5] [T6] [T11] [M1]
The destination's treaty
Canada's tax treaties decide who counts as resident when two countries both claim you, and they set or cap withholding on pensions and other Canadian income. The Department of Finance in-force list includes treaties with Portugal, Spain, Mexico, France, Italy, Thailand and Malaysia. Costa Rica does not appear on it. Whether your destination taxes your income at all is a question for its tax authority.
The guides for Portugal, Spain and Mexico describe each country's own rules, and Portugal and Spain sets two side by side. Which treaty applies to your RRSP, RRIF, CPP and OAS payments, and whether Form NR5 suits you, is worth settling with the CRA or an adviser before you go. [T2] [T5] [T7] [T12]
Fernshore articles explain published rules as of the dates shown in the sources. They are research, not legal, tax or financial advice for your situation.
Sources
- [T1] Leaving Canada (emigrants), Canada Revenue Agency. Checked 17 October 2026.
- [T2] Determining your residency status, Canada Revenue Agency. Checked 17 October 2026.
- [T3] Dispositions of property for emigrants of Canada, Canada Revenue Agency. Checked 17 October 2026.
- [T4] Income Tax Act, section 128.1 (emigration and immigration), Department of Justice Canada. Checked 17 October 2026.
- [T5] Non-residents of Canada, Canada Revenue Agency. Checked 17 October 2026.
- [T6] Electing under section 217, Canada Revenue Agency. Checked 17 October 2026.
- [T7] Tax treaties, Canada Revenue Agency. Checked 17 October 2026.
- [T8] How non-residency affects your TFSA, Canada Revenue Agency. Checked 17 October 2026.
- [T9] Non-residents and FHSAs, Canada Revenue Agency. Checked 17 October 2026.
- [T10] Information Circular IC76-12: Applicable rate of Part XIII tax on amounts paid or credited to persons in countries with which Canada has a tax convention, Canada Revenue Agency. Checked 17 October 2026.
- [T11] Important reminder if you filed Form NR5, Canada Revenue Agency. Checked 17 October 2026.
- [T12] Tax treaties in force, Department of Finance Canada. Checked 17 October 2026.
- [M1] Taxes: foreign and Canadian pensions and benefits, Service Canada. Checked 17 October 2026.
See what your situation makes possible.